Storm season in North Texas has a rhythm that most homeowners recognize but few act on quickly enough. A hard cell rolls through in April, the yard is littered with leaves and shingle granules for a day, and then life resumes. Nothing leaks. No ceiling stain appears. The assumption is that the roof survived and the phone call to a roofing contractor gets pushed to sometime this summer. In Boyd Texas where much of Wise County sits squarely inside what insurers call hail alley, that assumption is one of the most expensive mistakes a property owner can make.
The problem is that roofing damage is rarely dramatic on day one. Hail bruises the asphalt mat beneath the granules without breaking the surface. Wind creases shingles and breaks the factory seal strip while leaving them lying flat enough to look untouched from the driveway. Neoprene pipe boots crack in the summer heat and let a teaspoon of water in per rain event, enough to soak decking and grow mold long before anything reaches the drywall. By the time visible evidence arrives, the repair has quietly changed categories and so has the insurance claim attached to it.
This article walks through what waiting costs: the deadlines buried in a homeowner's policy, how damage compounds inside an attic, the shifting coverage terms carriers are writing into North Texas renewals, and the dollar difference between an early repair and a delayed replacement. It also covers how a property owner in Boyd and Springtown Texas or the surrounding area should evaluate a roofing contractor after a storm and what a real post-storm inspection should include.
The Clock Starts the Moment the Storm Passes
Homeowners tend to think of an insurance claim as something they can file whenever they get around to it. Policies are written differently. Nearly every carrier requires prompt notice of a loss and Texas law limits a suit on a claim to two years from the date of loss. Those two facts alone reward speed, but they are not the expensive part.
Prompt Notice, Deductibles, and the Language Carriers Actually Use
Carriers routinely reduce or deny claims when delays let roofing damage worsen. The argument is straightforward: if a wind event broke seal strips in May and the homeowner reported it in November after three more storms, the adjuster can attribute part of the loss to neglected maintenance rather than the covered event. A roofing contractor working in the Boyd Texas area sees this pattern constantly: a legitimate hail claim gets carved up because nobody documented the damage while it was fresh and attributable to a single dated event.
There is also a legal boundary worth naming plainly. Under Texas Business and Commerce Code §27.02, it is illegal for a roofing contractor to pay, waive, absorb, or rebate a homeowner's insurance deductible. Any crew offering to cover your deductible is proposing something unlawful and the homeowner is exposed alongside them.
The RCV Depreciation Homeowners May Need to Finish the Job
With a replacement-cost value or RCV policy, the insurer may initially pay the actual cash value or ACV of the covered damage, meaning the estimated replacement cost minus depreciation and the deductible. Once the covered roofing repairs are completed and the required documentation is submitted, the insurer can release the recoverable depreciation.
That second payment can be important because homeowners may rely on it to pay the remaining balance owed to their roofing contractor. For example, if a $20,000 roof replacement includes $5,000 in recoverable depreciation, the initial insurance payment may not provide the full amount needed to complete the project. The homeowner may need the depreciation payment after the work is completed to satisfy the contractor's final invoice.
The exact process and deadline vary by policy and carrier. Homeowners should confirm how much depreciation is recoverable, what documentation is required, and how long they have to complete the work. Waiting too long could create cash-flow problems or depending on the policy terms, jeopardize the ability to recover some depreciation.
For homeowners with an approved RCV claim, understanding when the depreciation will be released can be just as important as knowing the total replacement-cost amount.
What Actually Happens to a Roof While You Wait
Roof systems fail at their transitions, not in the middle of the field. Understanding those points explains why waiting until next spring costs more than it saves.
The Quiet Failure Points
Attic temperatures in a Wise County summer routinely reach 130 to 150 degrees, which accelerates sealant failure and shingle aging. The components that give out first are small, cheap, and easy to miss:
- Neoprene pipe boots, which typically crack and split somewhere in the 8 to 12 year range
- Lifted shingles with broken seal strips that reseal poorly or not at all
- Valley metal that has lost coating or shifted at the laps
- Chimney counterflashing that has pulled away from the mortar joint
- Exposed-fastener flashing at HVAC curbs where gaskets shrink and back out
- Nail pops that telegraph through the shingle above them
- Wind-creased shingles that look completely intact from the ground
None of those will announce themselves. All of them let water past.
From Damp Decking to a Five-Figure Interior Repair
Once water reaches the OSB decking, the material swells, delaminates, and does not recover when it dries. Mold can establish in a humid attic within 24 to 48 hours. A roof that needed a $350 to $1,500 repair in May can, by the following spring, require decking replacement at roughly $70 to $150 per 4x8 sheet, plus interior work.
Drywall, insulation, and paint repair from a single undetected leak commonly runs $500 to $3,000 or more. Add insulation that has been compressed and contaminated, framing that needs treatment, and the cost of moving furniture as well as living around the work, and the arithmetic stops being close. Roofing damage is one of the few home problems where the repair cost curve bends sharply upward with time rather than staying flat, which is why homeowners in Boyd and Springtown Texas are better served by an inspection they did not strictly need than by a repair they waited too long to schedule.
The Insurance Landscape Is Tightening
Even homeowners who understand the deadlines underestimate how quickly coverage terms are changing across North Texas. Waiting until the next renewal can move a roof out of full coverage entirely and no roofing contractor can undo that after the fact.
Carriers in this region are increasingly writing:
- Separate wind and hail deductibles set at one to two percent of the dwelling amount rather than a flat dollar figure
- Cosmetic damage exclusions which pay for function-affecting damage but not dented metal or marred surfaces
- Actual cash value roof schedules for roofs over ten to fifteen years, eliminating replacement cost entirely
- Tighter documentation requirements and shorter completion windows on approved claims
A fourteen-year-old roof that carries full replacement cost today may be endorsed onto an ACV schedule at the next renewal. The same hail event, evaluated a year apart, produces two very different checks. Property owners in Springtown Texas who have been meaning to have their roof looked at should understand that the policy they are relying on may not be the policy that renews.
What Delay Costs in Real Numbers
It helps to put the two paths side by side. Path One: a homeowner calls a roofing contractor after an April hail event, gets a documented inspection, files within weeks, and completes the work within the carrier's window. Path Two: the same homeowner waits.
On Path two, the repair scope grows to include decking. The claim may be reduced for late notice. The depreciation holdback may lapse. The interior now needs drywall and paint. The roof may have aged past the policy's replacement-cost threshold in the interim. And because two more storm seasons have passed, separating the covered event from ordinary wear becomes an argument the homeowner is unlikely to win.
Gutters follow the same logic. Mature oaks and pecans around older properties drop debris that clogs downspouts, backs water up under the drip edge, and rots fascia. Replacing 5-inch K-style aluminum gutter typically runs $8 to $15 per linear foot and 6-inch runs $10 to $20, with guards adding roughly $10 to $30 per linear foot, modest numbers next to rotted fascia, soffit, and soaked wall sheathing. Roofing and gutter work are a single water-management system and in Boyd Texas and nearby Springtown, the failure of one usually shows up as damage attributed to the other.
Repair or Replace: Where the Line Falls
Not every call ends in a replacement and any honest roofing contractor will say so. The line generally falls along these considerations: the age of the shingle line, whether damage is isolated to a slope or distributed across all elevations, whether hail has fractured the mat, and whether the existing system can be repaired without violating current code requirements.
That last point matters more than most homeowners realize. A quick patch often skips code items that a proper installation includes such as drip edge as required under IRC R905.2.8.5, a six-nail high-wind fastening pattern, and attic ventilation balanced at 1:150 or 1:300 where balanced intake is present. A patch that ignores those items may stop today's drip while leaving the assembly non-compliant and the next claim harder to defend.
Hail severity is also a factor. Stones around one inch can bruise asphalt shingles; 1.75 inches and above is considered severe. Bruising is frequently invisible until granule loss and mat fracture progress, which is precisely why saying that there is no stain on my ceiling is not evidence that a roof is sound.
What a Thorough Post-Storm Inspection Includes
A meaningful roofing inspection takes roughly 45 to 90 minutes and produces documentation the homeowner keeps, whether or not they file a claim. It should cover:
- Test squares on each slope to establish hail hit density and pattern
- Soft metals including gutters, vents, flashing, and downspouts as collateral evidence of stone size
- Every penetration: pipe boots, HVAC curbs, chimney counterflashing, skylights
- Seal strip integrity and creasing along ridges, hips and rakes
- Valley metal, drip edge and eave conditions
- Attic decking, insulation and framing for staining, delamination and daylight
- Ventilation math for intake and exhaust
- Dated photographs tied to the storm event
Because much of Wise County is unincorporated, residential re-roof permits are often not required, which means the rigor of the inspection and installation falls entirely on the company doing the work. That is a strong argument for hiring a roofing contractor with an established local presence in Boyd and Springtown Texas rather than whoever knocked on the door first.
Checking Out Help After a Storm
Texas does not license roofing contractors. RCAT registration exists, but it is voluntary, so there is no state credential to verify. That vacuum is why out-of-state door-knocking crews reliably appear after every major hail event in the area.
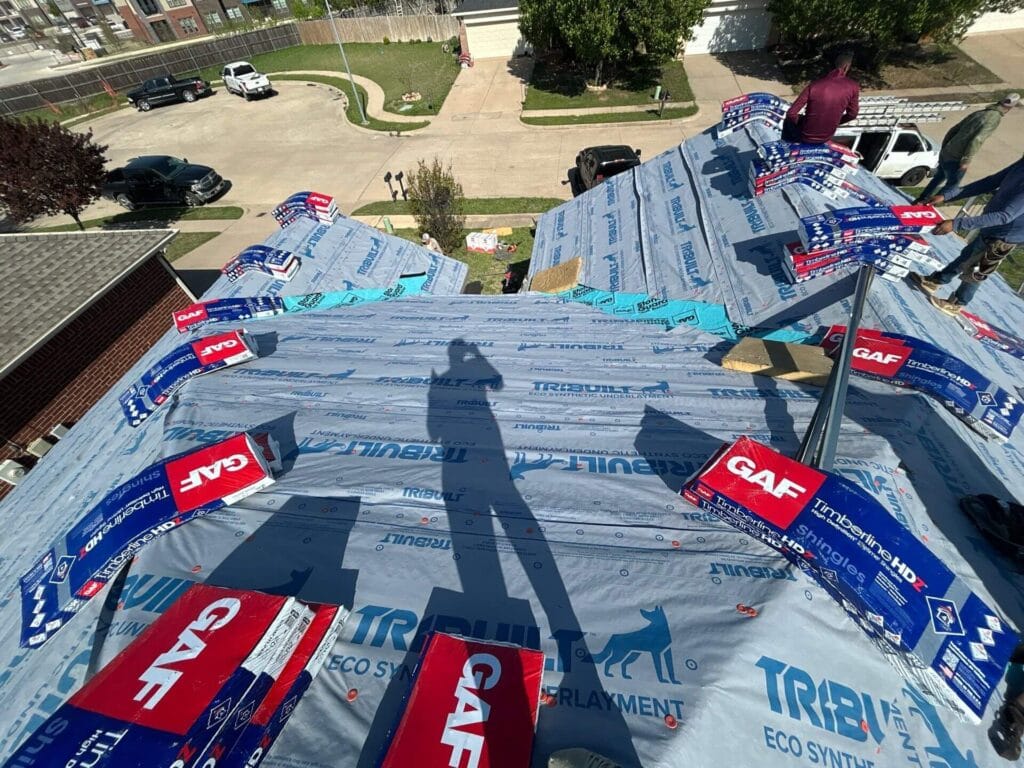
Homeowners should verify a certificate of general liability and workers compensation insurance directly from the carrier or agent, confirm a physical local address, ask for the manufacturer certifications the company actually holds, and get the full scope in writing including underlayment type, fastening pattern, ventilation plan, flashing details, and warranty terms. Synthetic underlayment versus 15-pound felt, ridge vent versus off-ridge vents, and ice-and-water membrane at valleys and eaves are all scope decisions that belong on paper, not in a handshake. A qualified roofing contractor serving Boyd and Springtown will put those specifics in the proposal without being asked.
Insurance supplement cycles typically take two to eight weeks and a single-family tear-off and install usually takes one to two days. Roofing crews in Boyd Texas and neighboring Springtown book out fastest between March and June, with a secondary rush in October, so waiting means not only a worse claim but also a longer queue. Winter events like those in February 2021 and January 2024 add ice loading and freeze-thaw stress at flashing, and often produce leaks that get misdiagnosed as burst pipes.
Final Thoughts
Roofing damage does not stabilize while a homeowner decides what to do about it. Instead, it compounds and the insurance mechanisms designed to pay for it come with deadlines that quietly expire. A bruised shingle becomes a soaked deck, a covered claim becomes a maintenance dispute, and a recoverable depreciation check becomes money the carrier keeps.
The single most cost-effective move after any hail or high-wind event in Boyd Texas, Springtown, and throughout Wise County is a documented inspection by a qualified roofing contractor while the damage is fresh and clearly attributable to a dated storm, even when nothing appears wrong from the ground. Property owners who schedule that inspection now preserve every option including repair, replacement, full claim value, and current coverage terms. Waiting removes those options one by one, and none come back!
Key Takeaways
- Most replacement cost policies release the depreciation holdback only after work is completed and invoiced, commonly within 180 days to one year of the loss, so delay can forfeit thousands of dollars already approved.
- Hail bruising and wind-broken seal strips are usually invisible from the ground, which means the absence of a ceiling stain is not evidence that a roof is undamaged.
- A leak that costs $350 to $1,500 to repair early can grow into decking replacement at roughly $70 to $150 per sheet plus $500 to $3,000 or more in interior repairs.
- North Texas carriers are adding 1 and actual-cash-value schedules for roofs over 10 to 15 years old, so waiting for renewal can reduce coverage.
- Texas does not license roofing contractors, so homeowners should verify liability and workers compensation certificates, a local physical address, and a written scope of work instead of a state credential.
- In Texas, it is illegal for any contractor to pay, waive, or rebate a homeowner's insurance deductible, and an offer to do so is a clear warning sign.
Frequently Asked Questions
There is no stain on my ceiling so how can I have roof damage?
A roof can be significantly damaged with no interior evidence. Hail fractures the asphalt mat beneath the granules, and wind breaks the adhesive seal strip between shingle courses; both allow gradual water entry that soaks decking and insulation long before it saturates drywall. Attic inspection and test squares on the roof surface are how that damage is actually found.
Will filing a claim raise my premium or get me non-renewed?
A weather-related claim is treated differently from a liability or repeated-loss claim, though carrier practices vary, so homeowners should ask their agent directly. What is certain is that an unrepaired roof creates its own non-renewal risk, since underwriters increasingly inspect roof condition and restrict coverage on aged or damaged systems.
If my roof is 14 years old, will insurance still pay replacement cost?
It depends entirely on the endorsements attached to the policy, and this is the age range where coverage most often changes. Many North Texas carriers move roofs past ten to fifteen years onto actual cash value schedules at renewal, which pays the depreciated value rather than the cost of a new roof.
Can the roof just be patched until spring?
A temporary repair is sometimes appropriate for an active leak, but it should be understood as triage, not a solution. Patches frequently skip code-required items such as drip edge, correct fastening patterns, as well as balanced ventilation and they do nothing to preserve claim deadlines that may expire before spring arrives.
Is my hail damage considered cosmetic under my policy?
Cosmetic damage exclusions generally apply to appearance-only damage such as dented metal, not to functional damage like fractured shingle mats or granule loss that shortens roof life. Policy language and inspection documentation determine the distinction, which is why detailed photographs and test squares matter so much.
Do I need a permit for a re-roof in unincorporated Wise County?
Residential re-roof permits are often not required in unincorporated portions of the county, but you should always confirm requirements for the specific address. Without municipal inspection, the installation's quality depends entirely on the roofing company's standards and documentation.
How long after a storm can a claim still be filed?
Policies require prompt notice and Texas limits suits on a claim to two years from the date of loss, but practical deadlines arrive much sooner. Carriers often deny claims when delays let damage worsen and it becomes nearly impossible to separate one storm from the next after another season passes.
How long does an inspection and a full replacement take?
A thorough inspection typically takes 45 to 90 minutes and a single-family tear-off and installation usually takes one to two days. Insurance supplement cycles, when additional scope is discovered, generally add two to eight weeks to the overall timeline.